Off-Road Diesel Compliance: Dyed Diesel Rules, Inspections and Penalties
Who may burn dyed diesel, how IRS and state inspectors check for it, what a violation costs, and who pays. Plus the records, labels and fleet controls that keep you out of trouble.
Off-road diesel compliance means dyed diesel goes only into nontaxable uses, such as off-road equipment, generators and farm machinery, never into a vehicle registered for public roads. IRS and state inspectors sample tanks at terminals, yards and roadside sites. The federal fine for using off-road diesel on the road is $1,000 or $10 a gallon, whichever is greater, and it grows with repeat violations.
Not tax or legal advice. This is general information about federal and state dyed fuel rules, not tax or legal advice. FuelGo is a fuel supplier, not a law firm or tax advisor. Check with an attorney or tax professional about your own situation.
Under Executive Order 14435 and IRS news release IR-2026-122, the IRS won't impose federal dyed-fuel penalties for highway use from October 1 through December 31, 2026, and has paused federal inspections of on-road dyed fuel use. It's a deferral, not a repeal: the tax isn't forgiven, and state taxes, penalties and inspections still apply unless your state has acted.
What the order does, what's still open and which states have matched it: dyed diesel on highways, the October 2026 executive order. This page covers the normal rules, which apply again after December 31, 2026 unless the relief is extended.
Who can use off-road diesel, in one paragraph
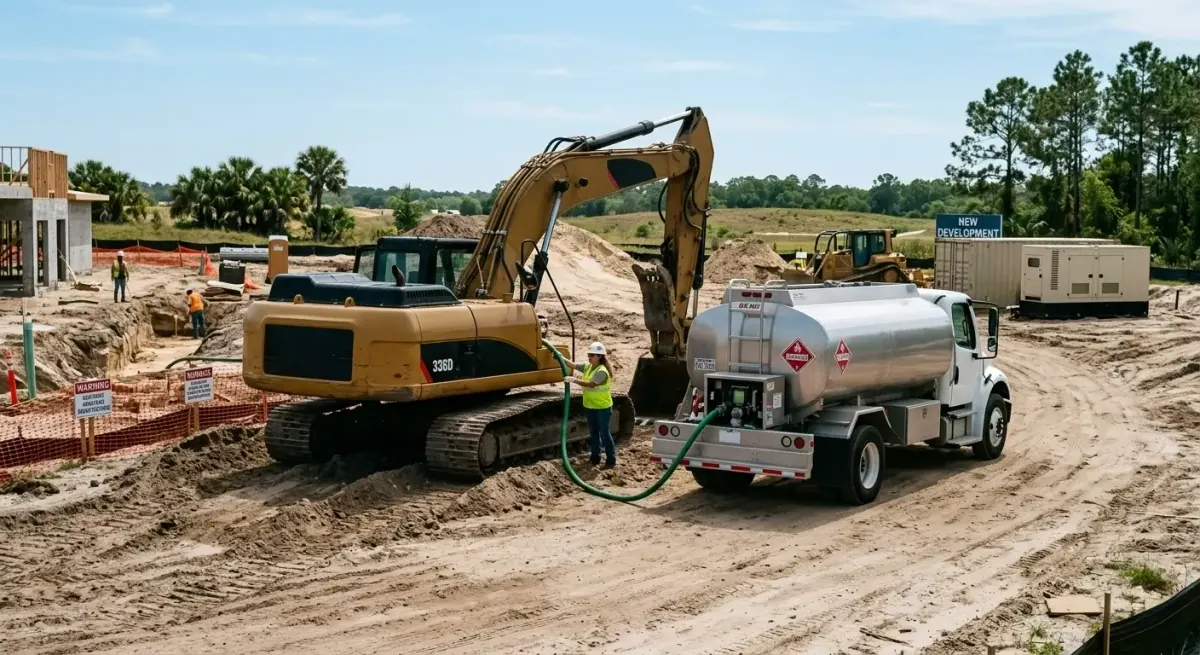
Dyed diesel was sold without the 24.3¢ federal excise, so the law lets it go only to a nontaxable use (26 U.S.C. 4082). IRS Publication 510 lists them: off-highway business use such as construction equipment, forklifts and generators; farming on the farm; trains; heating; school buses and exclusive use by state and local governments; and a few more. What it can never fuel is a highway vehicle registered, or required to be registered, for public roads. Pub 510 defines a highway vehicle as any self-propelled vehicle designed to carry a load over public highways, and a public highway as any road that isn't a private roadway. The full use-by-use breakdown is in dyed diesel vs clear diesel. This page is about staying compliant once you have both.
EnforcementHow dyed diesel enforcement works
The tax code gives the IRS the right to enter any place where taxable fuel is produced or stored, detain any container that may hold it, take samples and inspect records and shipping papers (26 U.S.C. 4083(d)). The regulation lists terminals, non-terminal storage, retail facilities and designated inspection sites such as state highway inspection stations, weigh stations, agricultural inspection stations and mobile stations (26 CFR 48.4083-1). Inspectors must show credentials and a written notice. The IRS staff who do this are fuel compliance officers, and the IRS manual describes where they look:
| Where | What inspectors do | What they're looking for |
|---|---|---|
| Terminals | Tour the facility, review shipping documents, take a sample of dyed fuel from transport compartments | Dye at the required strength, and the dyed-fuel notice on bills of lading |
| Retailers and wholesalers | Screen fuel from each diesel and kerosene tank at the nozzle | Dye in clear (taxed) pumps; the required notice on dyed pumps |
| Roadside inspection sites | Stop vehicles and fuel transports, usually at state inspection or weigh stations, and screen the vehicle's fuel tank | Red dye in the propulsion tank of an on-road vehicle |
| Company yards | Visit end users at their place of business; screen storage tanks and vehicles; review fueling records and practices | Dyed fuel feeding road vehicles; where each tank's fuel goes |
| Blitzes | Short, focused inspection drives on one area or industry. End-user blitzes sample dyed and clear storage tanks and screen all available registered diesel vehicles | Patterns across a region or trade |
| Farms | Check farm vehicles and storage | Dyed fuel in a farm vehicle is not penalized if the vehicle was on the farm and used for farming. Hauling to another farm on the road is |
Summarized from IRS Internal Revenue Manual 4.24.15 (Excise Fuel Compliance Inspection, Sampling, and Shipping).
At the truck, the check is simple. The officer slides a clean pipette into the fuel tank, seals the top with a thumb and lifts it to look at the fuel. No dye, the fuel goes back in the tank and the driver leaves. Visible red dye, the officer hands over IRS Publication 1 (Your Rights as a Taxpayer) and takes a "usage" sample, about one ounce, for the IRS Excise Forensics Laboratory. Dark or suspicious-looking fuel gets an "investigative" sample instead (IRM 4.24.15).
States run their own checks. California's tax agency (CDTFA), for example, inspects vehicle fuel tanks and bulk storage tanks, can penalize a refusal $1,000, and notifies the IRS when it finds dyed fuel in a road vehicle. Federal relief through December 31, 2026 doesn't stop a state inspection.
PenaltiesThe dyed diesel penalty: 26 U.S.C. 6715
Section 6715 covers four acts. Each carries the same penalty: the greater of $1,000 or $10 for each gallon of dyed fuel involved, on top of any tax due. The $1,000 floor goes up by $1,000 for each prior penalty against the same person, or a related or predecessor person. "Dyed fuel" means any dyed diesel or kerosene, whether or not it was dyed under the federal rules.
| What triggers it | Who it usually hits |
|---|---|
| Selling or holding dyed fuel for sale for a use you know, or have reason to know, is taxable | Sellers and distributors |
| Holding dyed fuel for use, or using it, in a taxable use while knowing, or having reason to know, it was dyed | The fleet, contractor or farm whose road vehicle burns it |
| Willfully altering, or trying to alter, the strength or composition of the dye or marker | Anyone who strips or dilutes dye |
| Selling or holding for sale fuel you know had its dye altered | Anyone downstream of laundered fuel |
What a violation costs: worked examples
| Situation | Penalty | How it's figured |
|---|---|---|
| Pickup with 30 gallons of dyed fuel, first penalty | $1,000 | $10 × 30 = $300, so the $1,000 floor applies. This is the IRS Chief Counsel's own example. |
| Truck with 150 gallons, first penalty | $1,500 | $10 × 150 beats the $1,000 floor |
| Same truck, second penalty | $2,000 | Floor is now $1,000 + $1,000 for one prior penalty, which beats $1,500 |
| Same truck, third penalty | $3,000 | Floor is $3,000. With two prior penalties, no administrative appeal is allowed except for lab fraud or error, or a math mistake |
| Plus the bulk tank that fueled it: 1,833 gallons | $18,330 | The Needsome Farms case: the IRS penalized the farm truck and the dyed fuel in the storage tank feeding it, and a federal court agreed that tank fuel held for a taxable use was "involved" |
Examples apply 26 U.S.C. 6715(b). The tax on the fuel (24.4¢ a gallon federal, plus any state tax) is owed on top. The 150-gallon truck rows are illustrations; the 30-gallon pickup and the 1,833-gallon tank come from IRS Chief Counsel Advice 201132023.
How the gallons get counted. The penalty is per gallon "involved," and that can be more than what's in the truck. IRS Chief Counsel says an examiner may start by presuming the whole storage tank is held for a taxable use. The presumption can be rebutted: with credible records showing what share of that tank historically went into off-road equipment, the IRS may assess only the rest (CCA 201132023, which isn't precedent). With no records, the whole tank is fair game. That's the strongest argument for the records below.
The tax is owed too. Dyed diesel delivered into the fuel tank of a diesel highway vehicle for a taxable use triggers the federal tax. Pub 510 makes the vehicle operator liable, and the seller jointly liable when it knows or has reason to know the fuel isn't for a nontaxable use. Refusing an inspection is a separate $1,000 penalty (26 U.S.C. 6717), and 4083(d) adds a $1,000-per-refusal forfeiture under section 7342.
LiabilityWho is liable: company, driver, supplier or all three
| Who | When they're on the hook | Source |
|---|---|---|
| The company | It held dyed fuel for, or used it in, a road vehicle. Usually the main target | 6715(a)(2) |
| Officers, employees and agents | Jointly and severally liable with the company if they willfully took part, such as the manager who ordered it or the employee filling a personal truck from the job tank | 6715(d) |
| The vehicle operator | Liable for the federal tax on dyed fuel delivered into the vehicle's tank | Pub 510 |
| The seller | Penalized if it sold knowing, or with reason to know, the use was taxable. Presumed to know if it didn't post the required dyed-fuel notice. Jointly liable for the tax in the same case | 6715(a)(1); 26 CFR 48.4082-2; Pub 510 |
| Anyone who alters dye | Willfully changing the dye, or selling fuel known to be altered | 6715(a)(3)–(4) |
| Parent companies | For the refusal-of-entry penalty, the parent of an affiliated group is jointly and severally liable too | 6717 |
Employee theft lands here too. Dyed fuel pumped from a job tank into a personal pickup is dyed fuel in a road vehicle, whoever paid for it. Our construction site fuel theft guide covers the controls that catch it.
RecordsWhat records to keep for dyed diesel
Inspectors visiting a yard review fuel delivery records, fueling records and how vehicles get fueled (IRM 4.24.15). Good records are also what lets you argue the gallon count down. Keep:
- Delivery tickets and invoices that show product (dyed or clear), gallons, date and site for every drop. See how to read a fuel delivery ticket.
- Which tank each delivery went into, so dyed and clear never blur on paper.
- Dispensing logs: date, gallons, unit ID, hour meter and who fueled, for every draw from a dyed tank.
- An equipment list that marks each unit off-road, registered for the road, or a separate motor with its own tank (reefer, welder, pump).
- Monthly reconciliation: gallons delivered against gallons dispensed against hours run. A gap is either theft or a leak into the wrong vehicle.
- Training sign-offs for drivers and operators, and any inspection paperwork: Publication 1, sample receipts, IRS letters.
How long? The IRS tells Form 720 filers to keep records supporting exemptions and claims at least 4 years from the latest of the date the tax was due, paid or claimed. Records for a Form 4136 credit are 3 years (see off-road diesel tax refunds). Four years covers both.
Storage & noticeStorage, labeling and the dyed fuel notice
The federal notice is a seller's duty. Any retail pump or other delivery facility where a seller sells dyed diesel for the buyer's use must carry a legible, conspicuous notice reading "DYED DIESEL FUEL, NONTAXABLE USE ONLY, PENALTY FOR TAXABLE USE" (26 CFR 48.4082-2). A seller that doesn't post it is presumed to know the fuel will go to a taxable use. Terminals must give the same notice to anyone receiving dyed fuel at the rack.
Some states put it on your tank. Illinois requires a legible and conspicuous notice reading "Dyed Diesel Fuel, Non-taxable Use Only" on all containers, storage tanks and facilities used to store or distribute dyed diesel, with a $500 penalty for the first occurrence and $1,000 after (35 ILCS 505/4f and 505/15). Even where your state doesn't require it, the federal wording on the tank and nozzle tells every driver what the fuel is for.
- One product per tank. A splash of dyed in a clear tank turns the whole tank red, and all of it is then dyed fuel.
- Label the tank and the nozzle, not just one of them.
- Lock dyed dispensers after hours, and restrict them by PIN or key fob to off-road unit IDs where you can.
- Flush before you convert. North Carolina's revenue department warns that dye remnants stay in a fuel supply tank. Drain and clean a tank, or a vehicle's fuel system, before it carries clear road fuel.
- Remember the other storage rules. Containment, spill plans and fire code are separate from tax rules. See diesel fuel storage regulations by state.
Running dyed and clear diesel in a mixed fleet
Most violations aren't schemes. They're the wrong nozzle, a borrowed gallon or a vehicle nobody thought about. Close those gaps:
- Map every unit. Off-road equipment and generators take dyed. Anything registered for the road takes clear. Write it down per unit ID.
- Find the gray areas before an inspector does. Pickups and service trucks that carry equipment on public roads. Farm trucks that leave the farm. Reefer units that draw from the tractor's tank instead of their own. Auxiliary tanks plumbed into the truck's own fuel system. A welder, pump or reefer with its own tank and motor can take dyed fuel; the truck's propulsion tank can't (Pub 510). Reefer rules differ by state; see reefer fuel delivery.
- Separate physically. Different tanks, different nozzles, clear labels, and dispensing access tied to the right units.
- Train and sign off. Drivers and operators should know what red fuel means, that a "borrowed" gallon from a machine is a violation, and that they can share the liability if they take part willfully.
- Audit like an inspector. Every so often, look at a sample from a few road vehicles' tanks. Red means fix it now, not at the weigh station.
- Take the tank out of the picture. With mobile fleet fueling, the driver fills road vehicles with clear diesel and equipment with dyed, unit by unit, and there's no shared tank to cross over.
What to do if you're stopped, sampled or fined
- Let the inspection happen. Refusing entry or sampling is its own $1,000 federal penalty (6717), plus the forfeiture under 4083(d). California charges $1,000 for refusing too.
- Get the paperwork. Keep Publication 1 and note the date, place, inspector, vehicle and sample. Samples go to the IRS lab; nothing is final at the roadside.
- Take the vehicle off dyed fuel. Drain and flush the tank and fuel system before it runs on public roads again. Dye remnants linger.
- Pull your records now. Deliveries, dispensing logs, the unit's history. They decide how many gallons are "involved" and whether a tank gets counted.
- Answer the 30-day letter. A proposed penalty arrives as Letter 3145 with Form 12009 and Notice 1215. Send Form 12009 within 30 days to ask for an informal conference; unresolved cases can go to IRS Appeals. Miss the window and you generally pay first, then claim a refund on Form 843 (IRM 4.24.16).
- Call a tax professional or attorney before you respond, especially if a storage tank or a prior penalty is involved.
- Fix the cause. The wrong nozzle, the shared code, the unlabeled tank. A third penalty can't be appealed except for lab or math errors.
Don't drive it on public roads until it's out. Drain the tank, flush the fuel system, refill with clear diesel, and write down what happened, when, how many gallons and what you did about it. The penalty turns on whether you knew or had reason to know the fuel was dyed. A dated record of what happened and how fast you fixed it is the best evidence you'll have.
State dyed diesel rules: examples
States set their own dyed fuel rules, and they don't all match the federal ones. A few examples from state law and revenue agencies:
| State | What's different | State penalty or tax | Clear vs dyed tax gap |
|---|---|---|---|
| California | CDTFA inspects vehicle tanks and bulk storage tanks; refusing an inspection or sampling can cost $1,000; the IRS is notified of dyed fuel found in road vehicles | Greater of $10 a gallon or $1,000 times the total number of penalties, including the current one; officers, employees and agents who took part are jointly liable | $0.7250/gal |
| Illinois | Tanks and containers holding dyed diesel must carry the "Dyed Diesel Fuel, Non-taxable Use Only" notice | Operator: $1,000 first, $5,000 each later occurrence. Knowingly possessing dyed diesel for highway use is a Class A misdemeanor, then a Class 4 felony | $0.8010/gal |
| Texas | Buying dyed diesel tax-free takes a comptroller end user number and a signed statement to your supplier, capped at 10,000 gallons a month (25,000 for agricultural off-highway equipment, or oil and gas production with a comptroller letter). Above that you need a dyed diesel bonded user license | State tax of $0.20 a gallon is owed on highway use. The governor's Sept. 28, 2026 disaster declaration (30 days, renewable) suspends the dyed diesel highway penalties but keeps that tax | $0.4444/gal |
| Alaska | The federal exception: diesel sold in Alaska for nontaxable uses doesn't have to be dyed, under certification procedures (26 U.S.C. 4082(c); IRS Notice 2010-68) | Check with the Alaska Department of Revenue | Not in our table |
Tax gaps are combined federal and state per-gallon taxes, clear minus dyed, from FuelGo's diesel taxes by state data as of October 16, 2026. Temporary suspensions aren't subtracted. Penalty terms are from each state's statute or revenue agency; confirm current rules before you rely on them.
The older claim that dyed diesel users need a permit "in states like Texas and Alaska" doesn't hold up as written. Texas does require an end user number, and a bonded user license above the monthly cap. We found no Alaska permit; Alaska's difference is the federal dyeing exception above. For which states have suspended dyed diesel rules in fall 2026, see the state relief list.
This page summarizes federal statutes and regulations, IRS publications and manuals, and state laws and agency guidance as of October 19, 2026. It is general information only and isn't legal, tax or accounting advice, and reading it doesn't create an attorney-client or any other professional relationship with FuelGo. Rules and the fall 2026 federal relief can change. Talk to an attorney or tax professional about your own situation, and confirm state rules with your state revenue department.
Dyed and clear diesel delivery, kept separate on paper
FuelGo delivers dyed off-road diesel for equipment, generators and farms, and clear on-road diesel for anything that drives on public roads, nationwide. Running a mixed fleet? We deliver both on the same account, often on the same route, and bill them as separate line items so your tax records stay clean. Deliveries are itemized by gallons, product and site, and delivery records and invoices are generated automatically. Gray areas, like a pickup that hauls equipment or a service truck that also runs a hydraulic pump, are worth a call to dispatch before the first drop.
With wet-hose fleet fueling, every fill is logged by unit. Need a dedicated dyed tank on site? Our rental tanks come with smart pump systems that track fuel use and control which drivers can draw fuel. Drops run from 20 to 4,400 gallons, with transport loads up to 7,500. Dispatch runs 24/7/365. Get a free quote or call 800-720-4546; a dispatcher replies within the hour.
Common questionsOff-road diesel compliance FAQ
What is the fine for using off-road diesel on the road?
Who can legally use off-road diesel?
How do inspectors check for dyed diesel?
Who is liable for a dyed diesel penalty: the company, the driver or the supplier?
How are gallons counted for the $10-a-gallon penalty?
Can I appeal a dyed diesel penalty?
Do I need a permit to buy dyed diesel?
Is dyed diesel legal on highways in 2026?
Sources: 26 U.S.C. 6715, dyed fuel penalty · 26 U.S.C. 4082, dyed fuel exemption and Alaska exception · 26 U.S.C. 4083(d), inspection authority · 26 U.S.C. 6717, refusal of entry · 26 CFR 48.4082-1, dye requirements · 26 CFR 48.4082-2, dyed fuel notice · 26 CFR 48.4083-1, inspections · IRS Publication 510, Excise Taxes · IRS Instructions for Form 720, recordkeeping · IRM 4.24.15, excise fuel compliance inspection and sampling · IRM 4.24.16, case processing and appeals · IRS Chief Counsel Advice 201132023 (Needsome Farms) · IRS IR-2026-122 (Oct. 14, 2026) · IRS Notice 2010-68, Alaska (archived) · Cal. Rev. & Tax. Code 60105 · CDTFA-500-DDF, Notice of Inspection · 35 ILCS 505/15, Illinois penalties · 35 ILCS 505/4f, Illinois tank notice · Tex. Tax Code 162.206, signed statements · Texas Comptroller, diesel fuel tax · NCDOR dyed diesel notice. Tax gaps from FuelGo's diesel taxes by state data as of October 16, 2026. All information as of October 19, 2026.